How does an ETF differ from an investment fund?
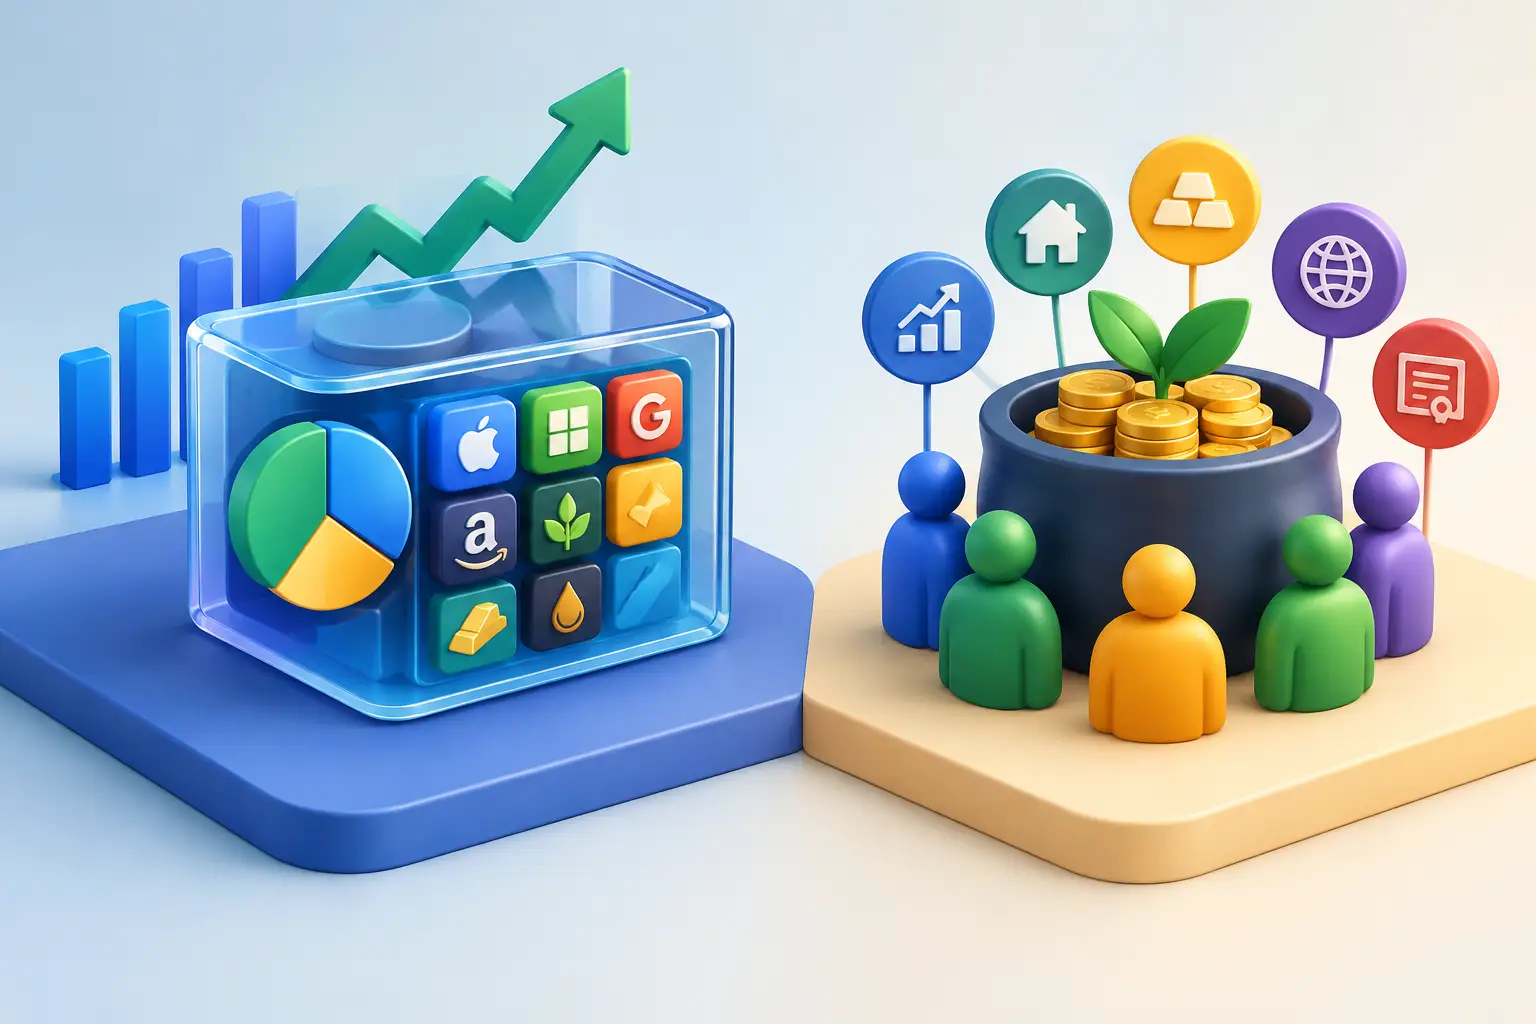
When an investor says they're putting money "into a fund," it's essential to clarify what type of fund they mean. The question - what's the difference between an ETF and a mutual fund - is often asked as if these were two completely different products. In reality, an ETF is itself a form of investment fund. The difference lies mainly in how it's bought and sold, how its price is formed, what costs it carries, and how actively it's managed.
These details aren't just terminology. They determine whether you'll be able to open a position at the moment you want, how much you'll pay in costs, and how well the instrument fits your investment plan.
What's the difference between an ETF and a mutual fund in practice
ETF stands for Exchange-Traded Fund - a fund that trades on an exchange. It pools capital from many investors and uses that money to buy stocks, bonds, commodities, or other assets. For example, one ETF might track an index of 500 major US companies, another might track the price of gold, and a third might track companies in the technology sector.
A traditional investment fund, often called a mutual fund, also pools investor money into a single portfolio. However, its units typically aren't traded on an exchange during the day. The investor submits a request to the fund, and purchases or redemptions are executed at the net asset value (NAV) calculated at the end of the day.
So the correct way to put it is this: ETFs and traditional funds serve the same purpose - building a diversified portfolio - but their mechanics differ.
Trading hours and price formation
Buying an ETF through a brokerage account works almost like buying an individual stock. If the exchange is open, you can place a market or limit order, monitor the current price, and have the trade executed within the same trading session.
With a traditional fund, you don't have a running price throughout the day. You might submit your order in the morning, but the exact price is only determined after the market closes, once the value of all the fund's assets has been recalculated. This doesn't bother many long-term investors, but for active management or the desire to enter at a precise price, an ETF is more flexible.
Here's one important nuance: an ETF's market price doesn't always exactly match its NAV. During strong demand, an ETF may trade at a small premium, while during weak demand, it may trade at a discount. For large, liquid ETFs this gap is often minor, but for narrow thematic, regional, or thinly traded funds, checking it is essential.
Liquidity: don't just look at trading volume
When discussing ETF liquidity, many people look only at daily trading volume. That's a useful metric, but it's not the full picture. An ETF's real liquidity is significantly tied to the liquidity of the underlying assets the fund holds.
For example, an ETF tracking a broad US equity index typically has a narrow bid-ask spread - the gap between buying and selling prices. Entering and exiting such an instrument is relatively efficient. A small-cap, exotic bond, or single-theme ETF may have a wider spread, which is a real cost to you even if the commission appears to be zero.
In a traditional fund, this problem exists in a different form. You're not trading with another investor on an exchange, and there's no spread, but you also can't sell your position mid-day. The choice here depends on whether you need operational access to your capital.
Costs and minimum investment
ETFs are often managed passively. Their goal is to replicate the performance of a specific index or sector, not to continuously "beat" it. Because of this, many ETFs have low annual expense ratios. Still, don't base your decision on this figure alone.
When using an ETF, factor in brokerage commissions, currency conversion fees, the bid-ask spread, and in some cases the cost of access to foreign markets. If you buy an ETF weekly with a very small amount and each transaction has a fixed commission, costs can end up consuming a significant portion of your portfolio.
A traditional fund may carry a high management fee, an entry or redemption commission, or a minimum initial contribution. On the other hand, some programs allow you to automate regular contributions and invest a precisely defined amount, say 100 GEL or 100 USD. When buying an ETF, you often need to account for the price of a single unit, unless your broker allows fractional share purchases.
Active and passive management: form and strategy aren't the same thing
A common mistake is assuming all ETFs are passive while all traditional funds are actively managed. In reality, either form can follow a passive or active strategy.
A passive fund tracks a predefined index. Its advantages are a transparent approach, broad diversification, and often relatively lower costs. An active fund's manager, on the other hand, decides which assets to buy, hold, or sell in order to beat the benchmark index or reduce risk.
Active management can be justified in certain segments, such as less efficient markets or complex bond strategies. However, it doesn't offer an automatic advantage. Higher fees and manager decision risk mean the result should always be compared to the relevant index, net of costs.
Transparency and portfolio control
Many ETFs publish their portfolio holdings daily or something very close to it. An investor can see exactly which companies, bonds, or other assets their money is invested in. This is especially useful when you already hold several positions and want to avoid unintentional overlap.
Traditional funds sometimes disclose their full portfolio composition less frequently. If a fund is actively managed, the manager may not want to reveal current positions on a daily basis. This isn't inherently a drawback, but investors should know what level of transparency they're getting.
In either case, check the fund's objective, benchmark index, geographic allocation, sector concentration, expense ratio, and largest holdings. The name is often not enough: a "global," "dividend," or "technology" fund can be built in very different ways.
Taxes and legal structure
There's no universal answer when it comes to taxes. The outcome depends on your tax residency status, your broker's jurisdiction, the country where the fund is registered, its dividend policy, and whether the fund has an accumulating or distributing structure.
A distributing fund pays out income to you periodically. An accumulating fund typically reinvests received dividends automatically back into the portfolio. Which is better depends on your goal: do you need ongoing cash flow, or long-term capital growth?
A Georgian resident investor should verify local declaration and tax rules with a qualified professional before choosing an international instrument. A brief tip from social media isn't a sufficient basis here.
Which option might suit you
An ETF is often a practical choice if you want to trade independently on an exchange, low-cost index exposure, intraday position management, and control over portfolio composition. This doesn't mean an ETF is automatically safe. Leveraged, inverse, or narrowly thematic ETFs can carry high risk and may prove much harder for a beginner to understand than a broad index fund.
A traditional investment fund may suit someone better who wants automatic regular contributions, isn't interested in daily price movements, and trusts a specific, well-reasoned active strategy. Even in this case, a detailed comparison of costs, performance, and redemption terms is essential.
Before choosing, ask yourself three questions: for how long am I investing this money, what's the total cost I'm paying, and how well do I understand the risk of the assets the fund holds? Traders' Hub's educational approach is built on exactly this habit - decisions should rely on data, risk management, and your plan, not noisy recommendations.
Choosing a fund's form is the start of your portfolio, not the final answer. The most valuable step is selecting an instrument whose mechanics you genuinely understand and which you'll be able to hold through periods of market volatility.