
An Example of Student Portfolio Growth Over 4 Years
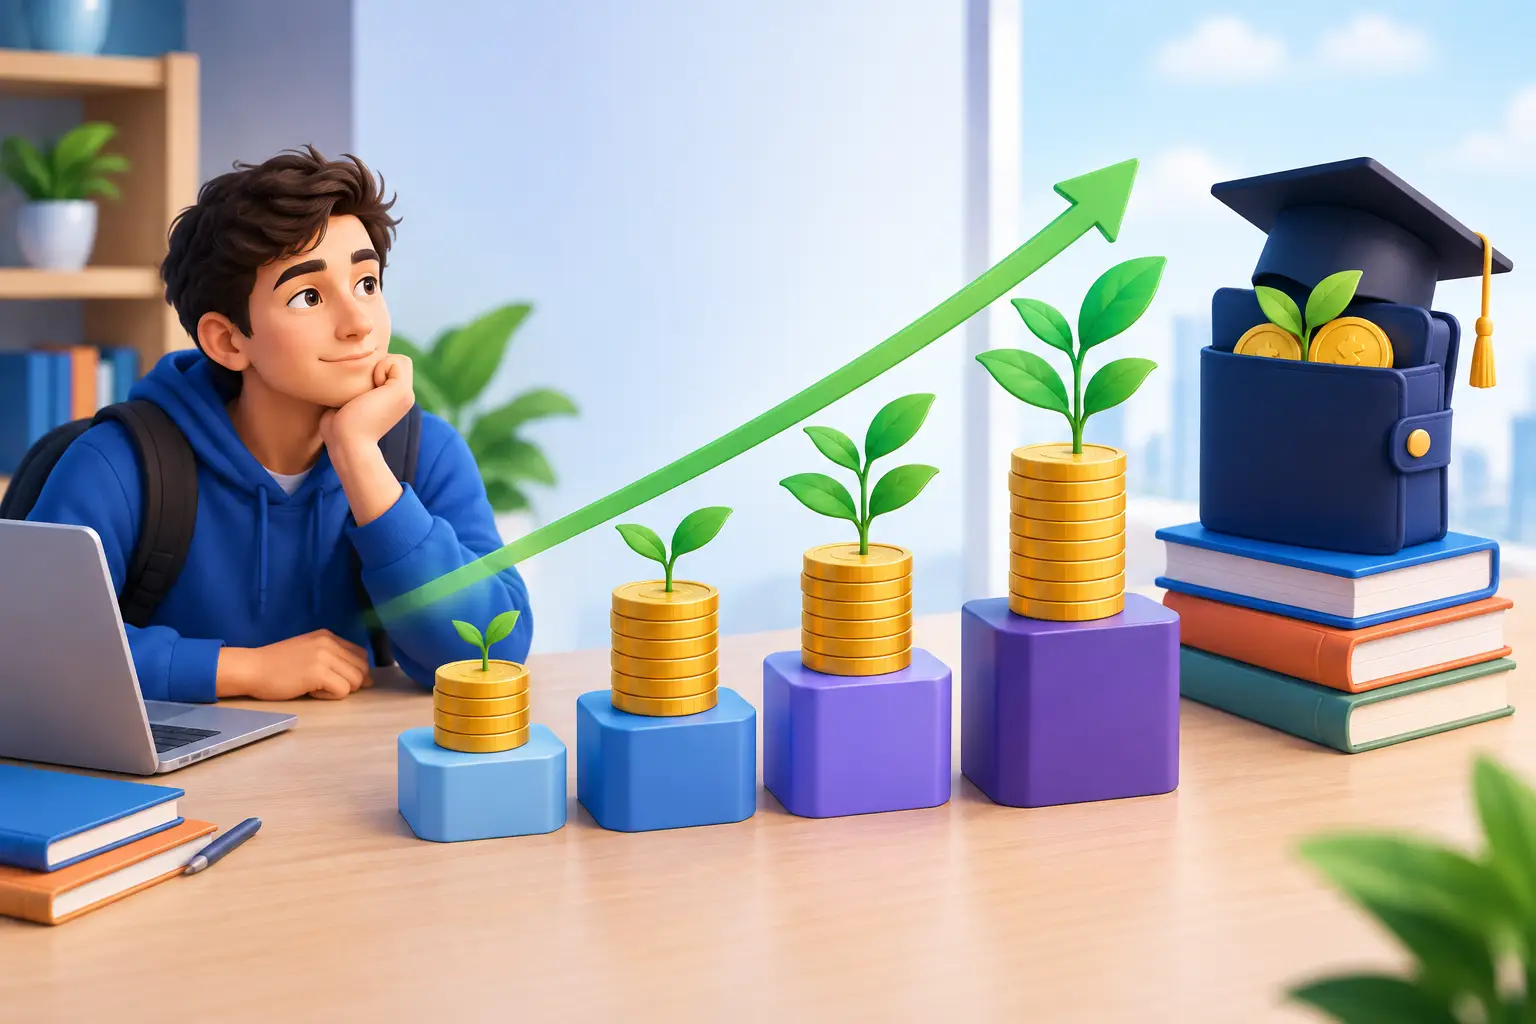
The example of a student's portfolio growth best illustrates one reality: the starting amount is often less important than the habit, the plan, and the attitude toward risk. An investment portfolio started by a student with 200 or 300 GEL won't turn into life-changing capital in one year. However, over four years, regular contributions, income growth, and control over emotional decisions already create a foundation that can keep working even after graduation.
This is not a get-rich-quick story, nor a guaranteed outcome. The case below is an educational model that shows how a student, within real financial constraints, can build a disciplined portfolio. Actual income, brokerage fees, exchange rates, taxes, and market results differ from person to person.
Starting Point: Small Amount, Clear Rules
Imagine a 20-year-old student, Nika, who studies in Tbilisi while working part-time. His income is unstable: during the semester he earns 850 GEL on average, while in summer he has a temporary job with higher income. He already has money set aside for three months of essential expenses, so he isn't starting to invest with borrowed money or his last savings.
Nika set four rules. In the first year, he contributes 150 GEL every month and adds another 600 GEL from his summer income. He doesn't use a credit card to invest, doesn't buy an asset based solely on social media advice, and doesn't change his plan because of a single week's price movement. The most important rule is this: money that will be needed for tuition, rent, or essential expenses within the next three years does not go into the portfolio.
Following these rules comes before technical analysis. If a student is forced to sell an investment during an emergency expense, a temporary market drop can turn into a real loss. That's why portfolio growth begins not with picking a stock, but with controlling one's personal budget.
The Example of a Student Portfolio's Growth, in Numbers
Nika's goal isn't to beat the market index in the short term. His goal is to build an investing habit over four years and accumulate capital that will give him extra financial flexibility at the start of his career.
In the first year, he contributes 2,400 GEL: 150 GEL each month plus 600 GEL in summer. The portfolio is mainly split between broadly diversified equity instruments and a relatively stable short-term cash reserve. For example, 75% is in long-term, broad-market-oriented instruments, 15% is in bonds or cash equivalents, and 10% is in a learning segment, where Nika researches individual companies with a small amount of money.
By the end of the year, the market might be up 8%, though this outcome isn't known in advance. In such a scenario, the portfolio's value would be approximately 2,550-2,600 GEL, accounting for contribution dates and fees. The main achievement here isn't a gain of 150-200 GEL. Nika followed his plan for 12 months and collected data about his own behavior.
In the second year, his income grows and he raises his monthly contribution to 220 GEL. In addition, he contributes 800 GEL in summer. Over the year, he will contribute 3,440 GEL in total. If the market this time drops by 10%, Nika's portfolio value may grow less than expected despite his contributions. This isn't a failure. On the contrary, with the same regular amount, he's buying assets at relatively lower prices.
In the third year, Nika starts an internship. Part of his income increases, but his free cash doesn't always grow - expenses for transport, equipment, or professional courses may also increase. So he keeps his contribution at 250 GEL and adds 1,000 GEL in summer. The annual contribution is 4,000 GEL. At this stage, his main task is no longer "polishing" the portfolio but maintaining the target allocation.
In the fourth year, if Nika's income has become more stable, he can contribute 300 GEL monthly and add 1,200 GEL over the year. The annual contribution reaches 4,800 GEL. Over four years in total, he has contributed 14,640 GEL. If the average annual return over this period, purely for illustration, is in the range of 6%-8%, the portfolio's estimated value could become approximately 16,500-17,500 GEL, depending on fees, exchange rates, and the performance of specific instruments.
These numbers don't mean the market will deliver a positive result every year. It's possible that in the first two years the portfolio would be worth even less than the amount contributed. The main driver of the long-term result in this example is Nika's disciplined contribution of 14,640 GEL, not a one-time discovery of a "perfect" stock.
Why a Portfolio Shouldn't Be Only Stocks or Only Crypto
Students are often drawn to the fastest-growing assets, since the desire for big results with small capital is natural. But high potential returns come with the price of high volatility. If a large part of the portfolio is in one crypto asset and its price drops by 50%, the expected recovery could take months or years. At that time, a student might need that very money for tuition, housing, or a career step.
Diversification doesn't eliminate risk, but it reduces the probability that one sector, country, or asset will damage the entire plan. Broad-market instruments, companies from different sectors, a certain cash reserve, and a moderate experimental portion form a more practical combination than a portfolio built on a single trend alone.
Allocation still depends on the goal. For a student who will need the money for tuition within two years, a large share in high-volatility assets is less suitable. A person whose goal is to build starting capital ten years from now, with relatively stable income, might hold a larger share of a growth-oriented portfolio. The right answer isn't always the same.
Portfolio Management: When Should a Student Change the Plan
In Nika's example, the allocation isn't checked every month. Frequent changes often lead to emotion, excess fees, and chaotic decisions. It's enough for him to review contributions, target weights, and his own financial situation once a quarter, and to do a more in-depth review once a year.
If the equity portion has risen from 75% to 85% after strong growth, new contributions can be directed toward the portion that has grown less. This is the simple logic of rebalancing: we don't buy only what turned out best yesterday, and we don't sell in a panic what has temporarily dropped.
Changing the plan is necessary when life circumstances change. Losing a job, rising tuition fees, the need to help family, or new debt shifts priorities. In such cases, the right decision might be to temporarily pause contributions and build up the reserve. Discipline doesn't mean blindly following the plan - it means making decisions based on facts.
Learning, Records, and Evaluating Real Progress
Portfolio value isn't a single metric. Nika should know how much he's contributed, how much he's earned or lost due to market movements, how much he's paid in fees, and what share each asset holds. A trading journal makes these records easier. A short note for every contribution - why he bought the asset, what risk he sees, and what has changed in his thesis - will save him from many costly mistakes in the future.
Learning also has a practical side. Watching the economic calendar helps a student understand why the market reacts to inflation, interest rates, or employment data. Market maps and sector comparisons show how one industry's movement differs from another's. In Traders' Hub's learning environment, this theory becomes easier to grasp alongside practical exercises and real market analysis.
Nika's four-year result might seem modest to some. But having more than 16,000 GEL in capital at the start of a career, an established budget, an understanding of risk, and decisions based on records is already a serious advantage. Start with an amount whose loss won't harm your everyday life, and build a system that market noise can't tear down.